Inland Marine Insurance in Connecticut: Protect Your Equipment
What inland marine insurance covers in Connecticut
Inland marine insurance in Connecticut protects business property that moves, gets stored off-site, or sits at locations your standard commercial property policy does not cover. Despite the name, it has nothing to do with boats or the ocean. The term is a holdover from the days when marine policies were the only way to insure goods in transit. Today it is the practical solution for contractors hauling tools to a job site in Shelton, manufacturers shipping finished goods to a distributor in Middletown, or a photographer carrying thousands of dollars of camera equipment to a shoot in New Haven.
A standard commercial property policy typically covers assets at a fixed, scheduled location. The moment your equipment leaves that address, coverage may stop. Inland marine fills that gap by following the property wherever it goes, whether across town or across state lines.
Who needs inland marine coverage in CT
Connecticut's economy runs on a wide mix of industries, and many of them move valuable property every day. If your business falls into any of the categories below, inland marine coverage is worth discussing.
- Contractors and tradespeople : Electricians, plumbers, HVAC technicians, and general contractors routinely carry expensive tools and equipment between job sites. A stolen generator or a compressor damaged in a jobsite fire is an out-of-pocket loss without inland marine.
- Manufacturers and distributors : Finished goods and raw materials moving through Connecticut's supply chain face theft, collision damage, and weather events during transit.
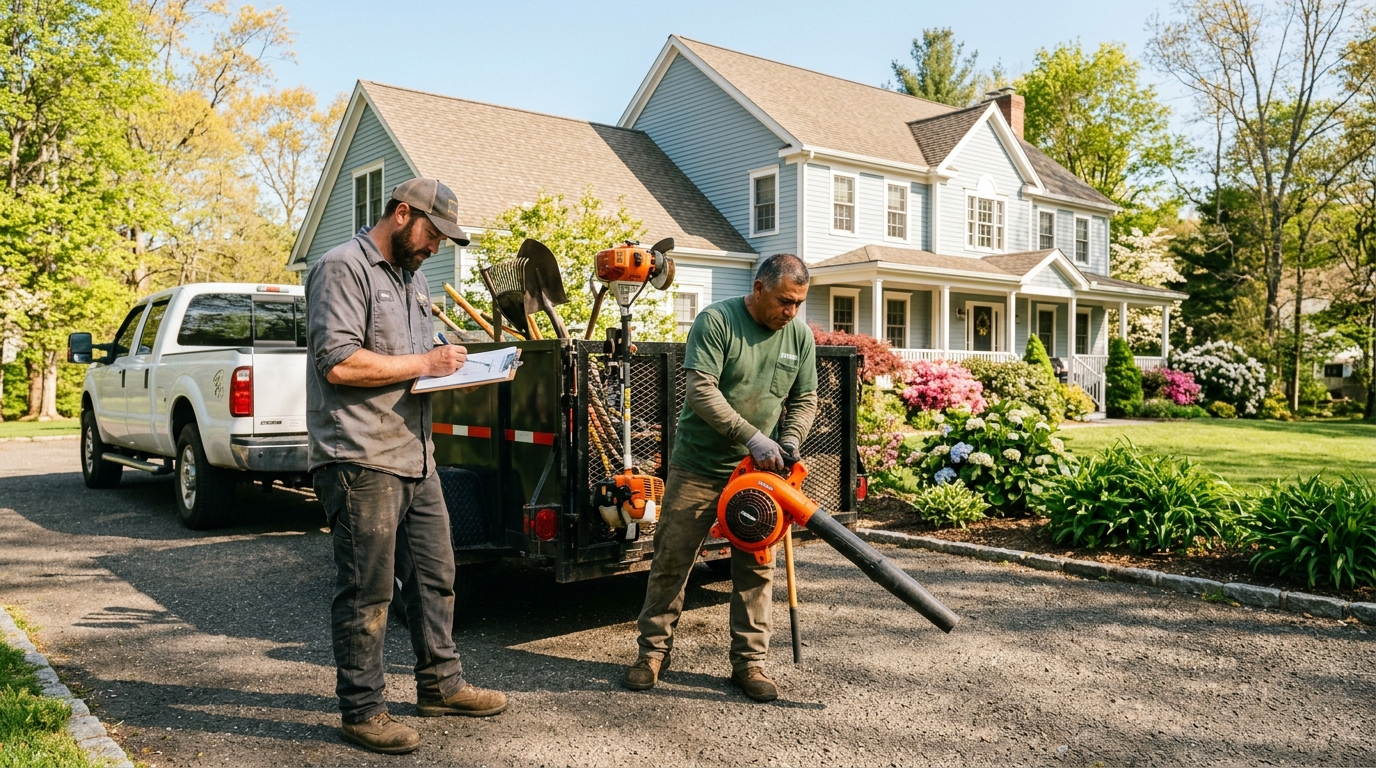
- Landscapers and excavators : Mowers, compact excavators, and skid steers travel constantly and represent serious capital investment.
- Photographers, videographers, and AV companies : Camera bodies, lenses, lighting rigs, and sound equipment are expensive and easy targets for theft at events or on location.
- IT and technology firms : Laptops, servers, and demonstration equipment traveling to client sites need protection beyond a general liability policy.
- Fine art dealers, galleries, and museums : Works on loan or in transit need scheduled coverage that reflects appraised value.
This list is not exhaustive. Any business that regularly moves property worth more than a few thousand dollars should evaluate whether a standard policy leaves a meaningful gap.
Types of inland marine policies and how they work
Inland marine is not a single, rigid product. Carriers write it in several forms depending on what property is being covered and how it moves.
Contractor's equipment floater
This is the most common form for Connecticut tradespeople and construction firms. It covers owned or leased equipment on a scheduled basis (specific pieces listed with agreed values) or on a blanket basis (a total coverage limit applied across all equipment). Perils covered typically include theft, fire, vandalism, and accidental damage. Heavy equipment like excavators can be written here even when it would fall outside a standard property policy.
Installation floater
An installation floater covers materials and equipment from the moment they leave a supplier's warehouse until the work is accepted by the property owner. For a contractor installing a commercial HVAC system in a Hamden office building, this bridges the coverage gap between the supplier's policy and the building owner's policy.
Builders risk
Technically a cousin of inland marine, builders risk insurance covers a structure under construction along with materials on-site and in transit. It is time-limited to the construction period and terminates when the building is occupied or the project is complete.
Motor truck cargo
This form protects cargo while it is being transported in a commercial vehicle. It is written for the trucker or freight carrier, not the shipper. If you are hauling goods for others, this is separate from a commercial auto policy, which covers the truck but not necessarily what is inside it.
Bailee's customer coverage
If your business takes custody of someone else's property, a bailee's policy protects you if that property is damaged or stolen while in your care. Dry cleaners, electronics repair shops, and furniture refinishers in Connecticut frequently carry this form.
Electronic data processing (EDP) coverage
Standard commercial property policies often exclude or severely limit coverage for computers, software, and data. An EDP floater extends coverage to hardware that travels and may include some data restoration costs depending on the carrier.
What inland marine does and does not cover
Like any insurance product, inland marine has boundaries. Understanding them before a claim prevents surprises.
Covered perils typically include:
- Theft : Including theft from a locked vehicle, which is a frequent claim for Connecticut contractors.
- Fire and lightning : Damage while in transit or stored off-site.
- Collision or overturn : If the vehicle carrying the equipment is involved in an accident.
- Vandalism : Deliberate damage at a job site or storage location.
- Flood and water damage : Depending on the policy form; confirm this with your agent because some forms exclude flood.
Common exclusions to watch for:
- Wear and tear or mechanical breakdown : A compressor that stops working because of age is not a covered loss. Insurance covers sudden, accidental damage, not maintenance failures.
- Employee dishonesty : Theft by your own employees is typically excluded from inland marine and requires a separate crime policy.
- War and nuclear hazard : A standard exclusion across virtually all property lines.
- Property in a vehicle left unattended overnight : Some forms restrict this or require a locked storage provision. Read the conditions carefully.
Deductibles on inland marine policies vary widely. A contractor might carry a $500 to $2,500 deductible on a tools floater, while a fine art policy might carry no deductible for scheduled pieces. The right deductible depends on how large a single loss you can absorb without disrupting operations.
How much inland marine insurance costs in Connecticut
Premiums depend on several factors that underwriters evaluate when quoting a policy.
- Total value of covered property : A landscaping company with $150,000 in equipment pays more than a photographer with $20,000 in gear. Accurate valuation matters, so do not underinsure to save on premium.
- Type of equipment : High-theft items like generators, chainsaws, and laptops cost more to insure than lower-risk categories.
- Geographic territory : If equipment travels only within Connecticut, premiums will differ from a policy covering multi-state transit routes.
- Claims history : Businesses with prior inland marine claims pay more. A clean loss history is a meaningful underwriting advantage.
- Security measures : Locked trailers, GPS tracking on equipment, and on-site storage security can reduce premiums. Carriers reward businesses that make theft harder.
- Deductible selection : Taking a higher deductible in exchange for a lower premium is a common approach for businesses with strong cash flow.
As a rough benchmark, contractors in Connecticut often see inland marine premiums ranging from $500 to $3,000 per year for coverage limits between $50,000 and $250,000, though those numbers shift significantly based on the factors above. An independent agent can run actual carrier quotes against your specific inventory so you are comparing real numbers, not ballpark estimates.
Inland marine and your broader commercial insurance picture
Inland marine rarely works in isolation. It is one piece of a complete commercial insurance program, and it fits alongside the policies most Connecticut businesses already carry.
Your commercial property policy anchors coverage for your building, permanently installed equipment, and business personal property at your listed location. Inland marine extends coverage for property that moves. Together they close the location-based gap.
A commercial auto policy covers the vehicle and liability when a company truck is involved in an accident, but it does not pay for the tools or cargo in the bed of that truck. Inland marine covers the contents; commercial auto covers the vehicle. Both are needed.
For contractors, a general liability policy covers third-party bodily injury and property damage claims arising from your work. It does not cover your own equipment. Inland marine fills that gap.
Many small and mid-sized Connecticut businesses also benefit from a Business Owner's Policy (BOP), which bundles property and general liability into one form. Some BOPs include limited inland marine coverage, but the limits are often too low for businesses with significant equipment inventories. A standalone inland marine floater with higher limits is frequently the better choice.
If your business has significant exposure across multiple lines, a commercial umbrella policy adds a layer of excess liability protection above your underlying limits. It does not replace inland marine but works alongside it to create a more complete program.
Get inland marine insurance quotes from United Insurance Group
United Insurance Group is an independent insurance agency serving businesses across Connecticut, from New Haven and Hamden to Shelton, Milford, Trumbull, and beyond. As an independent agency, we work with multiple carriers rather than being tied to one company's products. That means we can shop your inland marine coverage across several insurers, compare policy terms side by side, and recommend the option that fits both your operations and your budget.
If you are a contractor, manufacturer, landscaper, or any other business owner with equipment or cargo that leaves your premises, the gap in your coverage may be larger than you realize. We will walk through what you own, where it goes, and what it would cost to replace, then build a policy that matches your actual exposure.
Call us at (203) 795-0275 or visit our get a quote page to start the conversation. Protecting the equipment that drives your business is not something to leave to chance or to a policy that was not designed for the way you work.
Get A Quote
At United Insurance Group, securing your future is easy. Ready to protect what matters? Contact us for a quick quote and personalized insurance options!
Meet, James
Your 24/7 Insurance Assistant • English & Spanish
Start your custom insurance quote
Instant answers to your insurance questions
Schedule appointments or follow-ups
Personal Insurance
From auto and homeowners to renters and umbrella policies, we help protect your family and property. Let’s find coverage that fits your life.
Commercial Insurance
We customize policies for your industry's risks, like general liability and workers' comp, ensuring you can run your business worry-free.
Contact United Insurance Group
Recent Posts